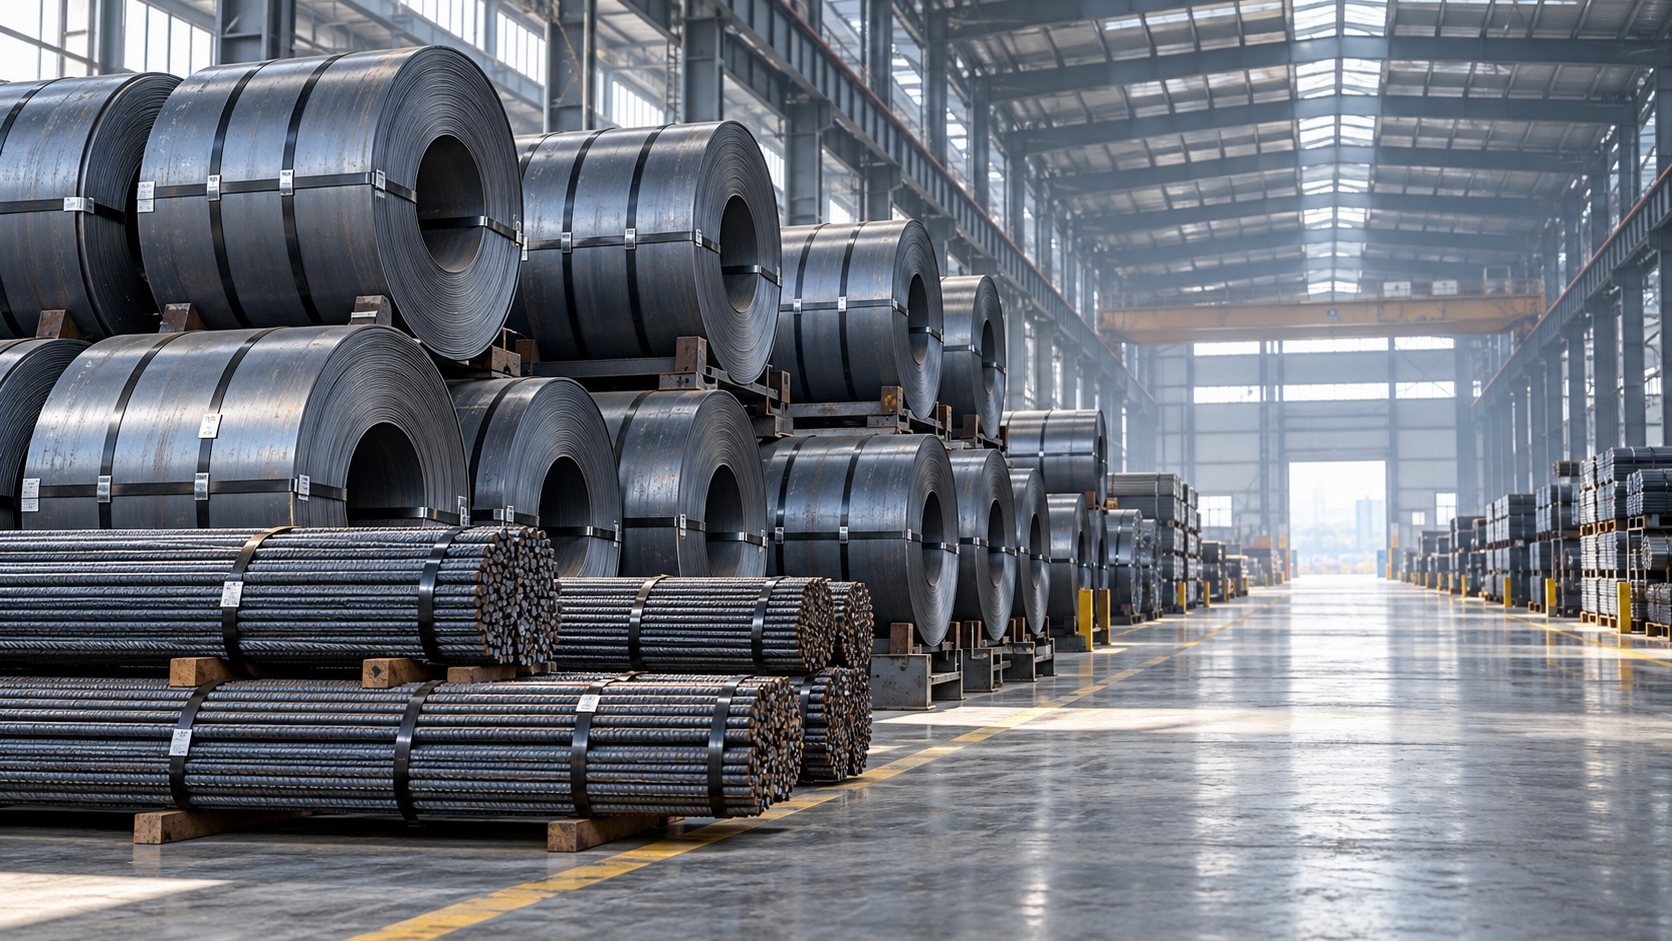
Steel social inventories across 21 cities fell in mid-October 2026, reversing the preceding accumulation trend, according to figures attributed to the China Iron and Steel Association in the supplied information. The change offers steel traders, processors and procurement teams a possible signal for reviewing purchasing and delivery plans. The supplied material identifies no accompanying policy, regulatory, certification or trade-rule change, so the inventory movement should be assessed as a market indicator rather than evidence of new compliance requirements.
Inventories Reverse Course but Remain Above the Start of the Year
The supplied figures show that social inventories of five major steel product categories across 21 cities totaled 8.96 million tonnes in mid-October 2026. This represented a decrease of 430,000 tonnes, or 4.6%, from the preceding reporting period, bringing the earlier inventory increase to a halt.
Despite that decline, inventories remained 1.75 million tonnes above the beginning-of-year level, an increase of approximately 24.3%. The supplied summary describes the reversal as indicating a marginal improvement in the balance between market supply and demand.
A Procurement Signal Without a Confirmed Change in Rules
Traders may need to reassess replenishment timing
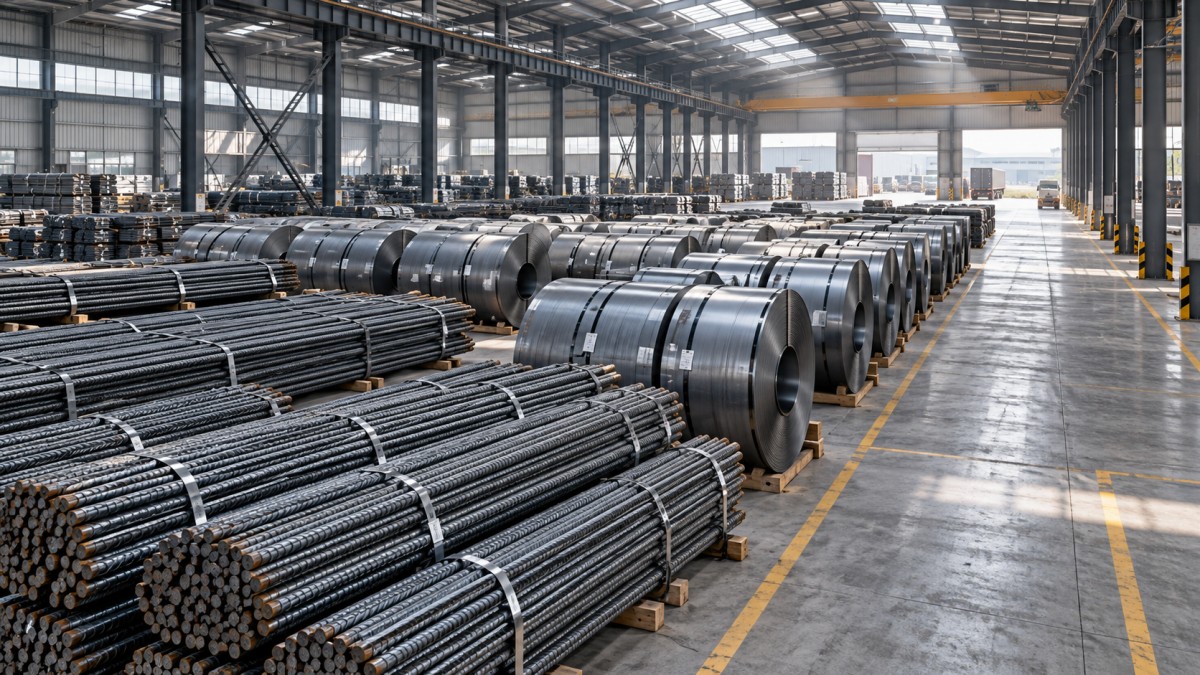
From an industry perspective, falling aggregate inventories may prompt steel traders and distributors to review the timing of replenishment and the stock available to support customer commitments. However, the supplied figures do not establish availability for individual products or locations. Any adjustment to purchasing or delivery commitments would therefore benefit from checking actual supplier stock and order conditions. No change to trade documentation or transaction requirements is identified in the input.
Processors should connect purchasing decisions to specific orders
Analysis suggests that processors and manufacturing buyers could use the inventory reversal as one input when reviewing material purchasing schedules. The relevance to an individual business would depend on whether its required products are experiencing a similar change in availability. Buyers could verify quantities, specifications and delivery dates with suppliers before adjusting procurement plans. The aggregate decline does not establish a change in product standards, testing requirements or supplier qualification criteria.
Delivery planning needs confirmation at supplier level
For supply-chain service providers and purchasing teams coordinating deliveries, the practical question is whether the reported decline corresponds to changes in material availability for their orders. As an operational consideration, confirming stock allocation and shipment readiness could help assess that possibility. The supplied information does not establish longer delivery periods, shipment restrictions or changes to acceptance procedures.
Three Checks Before Revising Purchase Commitments
Compare the aggregate movement with the products being purchased
As a practical recommendation, companies could compare the broad inventory signal with supplier information for the steel categories and specifications they actually buy. The supplied total does not include a product-by-product breakdown, so it cannot establish that every category experienced the same inventory decline.
Verify delivery terms before changing order schedules
Procurement teams could review confirmed delivery dates, available quantities and contractual scheduling provisions before accelerating or postponing orders. This is a suggested response to a possible change in market conditions; the supplied figures do not demonstrate that suppliers have changed their delivery terms or that buyers need to amend contracts.
Require separate evidence for any claimed compliance change
For compliance review, companies should distinguish inventory information from evidence of an amended rule. If a counterparty cites this development when proposing different certification, inspection or documentation conditions, buyers could request the applicable supporting document and verify its scope. No such amendment or implementation detail is provided in the input, so additional compliance obligations cannot be inferred from the inventory decline.
The Reversal Calls for Observation Before Broader Conclusions
As an editorial assessment, the decline is more appropriately understood as a market signal requiring continued observation than as a policy implementation milestone. A single reporting-period reversal does not establish a sustained reduction in inventories or explain the causes of the change.
The remaining increase of approximately 24.3% from the beginning of the year also matters when interpreting the figures. Analysis suggests that the recent decline and the higher inventory level relative to the start of the year should be considered together before drawing conclusions about procurement urgency. Subsequent comparable inventory releases, product-level information and supplier feedback would help businesses assess whether the movement is continuing and whether it affects their orders.
Use the Decline to Review Assumptions About Supply
The reported 4.6% reduction gives industry participants a reason to revisit assumptions about stock availability and purchasing timing. On the supplied evidence, the proportionate response is to verify conditions relevant to individual orders and monitor subsequent data. The figures support a cautious reading of marginal improvement in the supply-demand balance, while providing no basis for treating new regulatory, certification or trade requirements as established.
Basis of the Figures and Further Verification
This article is based solely on the user-provided news title, event timing and event summary. The supplied material attributes the inventory figures to the China Iron and Steel Association. A specific official source link was not provided in the input, and the underlying release and reporting scope remain subject to verification.
Further verification should focus on the relevant industry association release, subsequent comparable inventory data and industry feedback on purchasing and delivery conditions. Any later claim of a policy, certification or trade-rule change would require separate supporting documentation; none is identified in the supplied material.
By clicking 'Allow All', you agree to the storage of cookies on your device to enhance site navigation, analyze site usage and assist with our marketing efforts. Coo Cookie Notice